Summary
In this interview, Justin Huhn, founder of Uranium Insider, explains why he expects uranium prices to keep grinding higher until a contracting squeeze among tier-one producers triggers a sharper move, with another decade of the cycle still ahead. He supports the view with developments at Kazatomprom and Cameco, the Athabasca Basin development projects, current term-market contracting activity, and his positioning on uranium and nuclear equities.
Transcript
Key Takeaways:
- Kazatomprom Contracts: Two large contracts go to a Kazatomprom shareholder vote in early October, one with Chinese buyers and one long-term deal with Rosatom. Huhn says it is the first time Russia has bought uranium directly from Kazatomprom, estimates the volume at close to 20 million pounds, and notes that more than half of Kazatomprom's 2025 sales went to China.
- Sulfuric Acid Risk: Russia announced a halt to sulfuric acid exports, and Russia supplies 15 to 20% of Kazatomprom's annual acid needs. Huhn does not know whether Kazakhstan will receive an exemption, but if not, he expects higher production costs and possible production slippage.
- Western Utility Warning: Huhn says Kazakh management is telling Western utilities to contract now for 2032 to 2037 supply, because Kazatomprom is selling to the highest bidder, currently China, Russia, and India.
- Cameco Pipeline: Huhn says Cameco's mine plan has Cigar Lake mined out in the mid-2030s and McArthur River in the early 2040s, with the company sold out through 2030 and about half sold through 2035. He expects utilities seeking coverage from tier-one incumbents to start hearing "we don't have it," and sees that as a possible catalyst for a much sharper price move.
- Development Projects: Huhn expects Denison's Phoenix, the first attempt at ISR in hard rock, to produce 8 to 9 million pounds a year for four years starting in 2028. For NexGen's Rook I, he sees a 48-month build, first production in 2031, and full production in 2032, with the 29 million pounds a year in the feasibility study remaining unproven.
- Term Market Activity: Huhn points to Duke's RFP in August and a South Korean enrichment tender through 2039 covering roughly 25 million pounds of uranium equivalent. He says spot rose about five dollars a pound over the past couple of months and expects it to keep moving higher with pauses along the way.
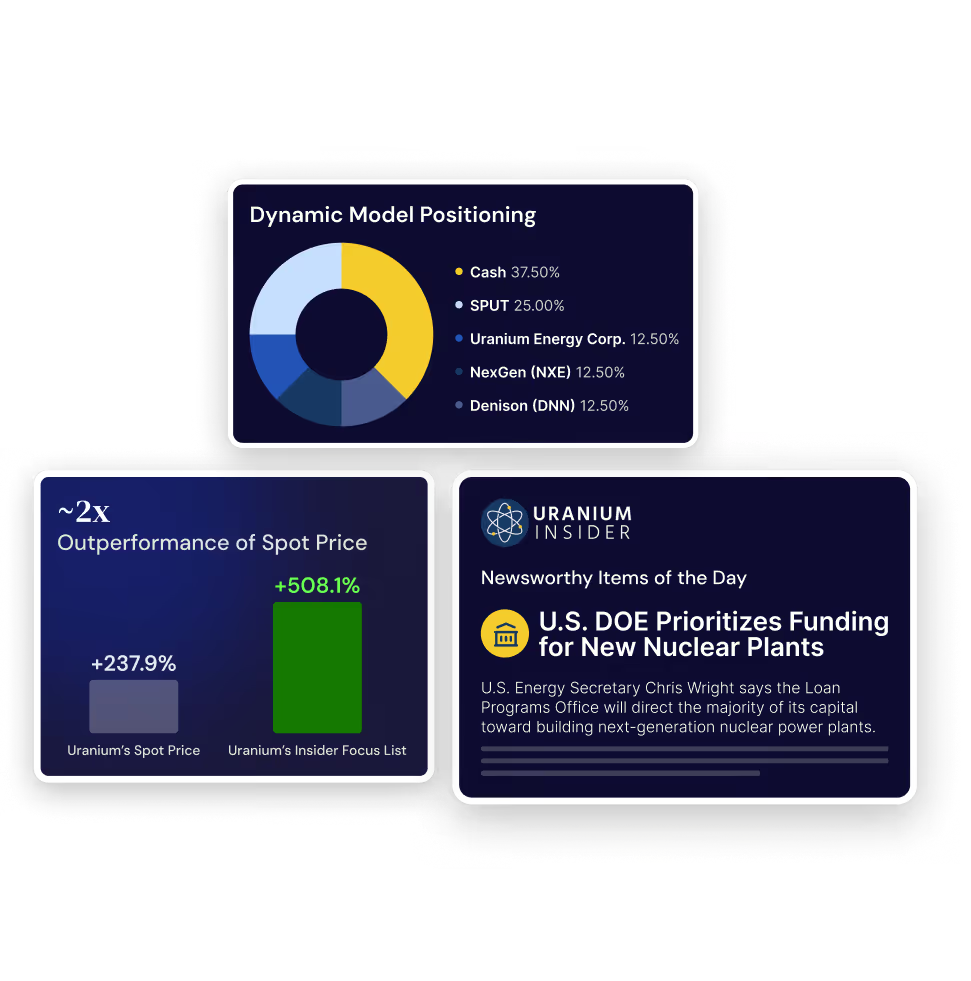
- Equity Positioning: Huhn considers uranium equities undervalued and short-term oversold, and cites a double-digit discount to NAV for SPUT. He favors slow accumulation of a nuclear equity basket including X Energy, Oklo, and BWXT, citing X Energy's binding agreements with Amazon, Dow Chemical, and Centrica and an expected NRC construction permit in the first quarter of next year.